
How to raise a credit score before buying a home
The app score is often not the lender's score. What moves a mortgage credit score, quick wins that often work, and what to avoid before buying in Texas.
Why is the score in a credit app often not the one a lender uses?
The score in a free credit app is often not the score a mortgage lender uses. App scores are usually VantageScores, while mortgage lenders have long used older FICO models that can grade more harshly. Many buyers see a gap of 15 to 50 points or more. Someone who thinks they are a 680 may turn out to be a 632, which can be too low for some Texas assistance programs.
Lenders typically pull all three bureaus and use the middle score, not the average. For couples, they generally use the lower of the two middle scores.
What makes up a credit score?
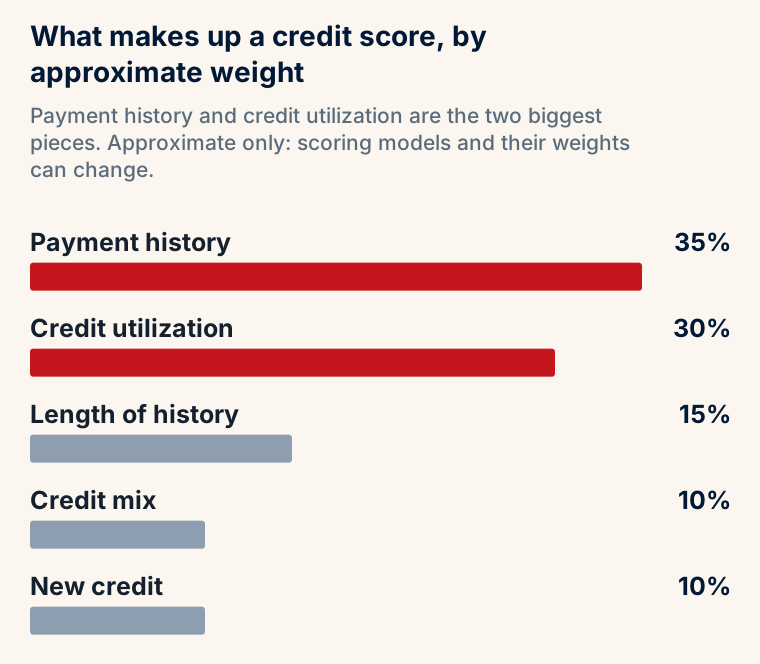
The good news: a credit score is a system, not a mystery. Here is what moves it.
| Factor | Approximate weight | What it means |
|---|---|---|
| Payment history | 35% | Late payments of 30 days or more are what typically report; a late fee alone usually does not |
| Credit utilization | 30% | How much of the card limits is in use; under 30% helps, under 10% is better |
| Length of history | 15% | Older accounts help, so avoid closing them |
| Credit mix | 10% | Having different types of credit can help |
| New credit | 10% | New applications can lower a score temporarily |
Which quick wins often work?
These are the quick wins that often work.
- Pay down high-utilization cards. Bringing a card from 90% used to under 30% can make a meaningful difference over a few months.
- Pay before the statement closes, so a lower balance is what gets reported.
- Ask for credit limit increases. A higher limit lowers utilization without spending less.
- Become an authorized user on someone else's long-standing, low-balance account, if a trusted family member offers.
What should a buyer not do before buying?
Before buying, avoid these moves:
- Applying for new credit, even a 0% offer
- Closing old accounts
- Financing furniture for a house you do not own yet
- Paying off old collections without advice first, since the timing and method can matter
- Co-signing for anyone
What score do Texas programs start at?
Many Texas assistance programs start at a 620 score. FHA can technically go lower, but those loans can come with larger down payment requirements, higher reserves and less favorable pricing. For buyers who are light on cash, aiming for 640 or higher gives more room.
What does a rough timeline look like?
The most useful first step is getting the real mortgage scores, ideally from a mortgage professional who can run a credit simulator to show which moves are likely to gain the most points. Do it well before you are ready to make an offer.
From there, a rough timeline:
| When | Focus |
|---|---|
| First 30 days | Bring card balances down |
| Around 60 days | Request limit increases and dispute genuine errors |
| 90 days and beyond | Address collections with a plan and keep building positive history |
And the honest part
This is general education, not credit, legal or financial advice and not a commitment to lend. How much any step changes a score depends on the full credit file, and score requirements vary by program and lender. Scoring models and their weights can also change. Verify your situation with a licensed mortgage professional.
Which options fit at this stage?
The two-minute quiz narrows the list to the options worth a closer look for someone in this position.